Tokyo 23 Wards Used Condo Asking Prices Fell for the First Time in 26 Months as the Correction Starts Downtown

- Capital圈74,540,000 yen+1.3%,连续上涨23个月;年增长率从30.5%降至29.6%再至27.4%,三个月连降
- 东京23区127,410,000 yen-0.8%,为26个月来首次下跌,东京都整体横盘于112,480,000 yen
- 外圈持续强劲:神奈川43,260,000 yen、埼玉32,520,000 yen创历史新高,横滨+2.6%、さいたま+2.3%
- 近畿圈35,790,000 yen+0.8%,连续13个月上涨;大阪市64,630,000 yen+2.1%,连续19个月但年增长率跌破30%;中部圈-1.0%,连续三个月下跌
- 与REINS数据互证:成交价5月先跌、开价6月跟跌——调整顺序走到第三步,半径暂限都心
While the Capital圈74,540,000 yen has seen a 23-month streak of increases with a +1.3% rise in June, Tokyo's 23区 saw its first drop in 26 months at -0.8%. The official report directly states that 'the central area is entering an adjustment phase.' Following the pattern: volume contraction → price decline → opening prices decline, this adjustment is currently limited to the center of town, with areas like Yokohama and Saitama continuing to set new highs in demand-driven markets.
[Conclusion] Tokyo Kantei reported a 6-month average price of 74,540,000 yen for second-hand apartments (per 70㎡) on July 23. The Capital圈 saw a +1.3% increase, marking the 23rd consecutive month of growth. However, the headline hides the fact that Tokyo's 23区 experienced its first drop in 26 months at -0.8%, directly stating 'the central area is entering an adjustment phase.' For the first time in over two years, the leading force driving Capital圈 prices has paused.
[Data Breakdown] While the overall Tokyo price remains flat at 112,480,000 yen (0.0%), the outer regions continued to set new highs: Kanagawa Prefecture saw a +1.4% increase and Saitama Prefecture a +0.9%. Yokohama (+2.6%) and Saitama City (+2.3%) also increased, while Chiba City saw a +1.1% rise. Year-over-year growth rates slowed: the Capital圈 dropped from 30.5% in April to 29.6% in May and further to 27.4% in June.
The Kansai region saw a +0.8% increase for the 13th consecutive month, with Osaka City's prices rising by +2.1% for the 19th straight month but dropping below 30% year-over-year (to 25.4% in June). Kobe saw a -0.4% drop. The Chubu region experienced a -1.0% decline for the third consecutive month, with Nagoya seeing two consecutive monthly declines as it struggled to cross the 30 million yen barrier.
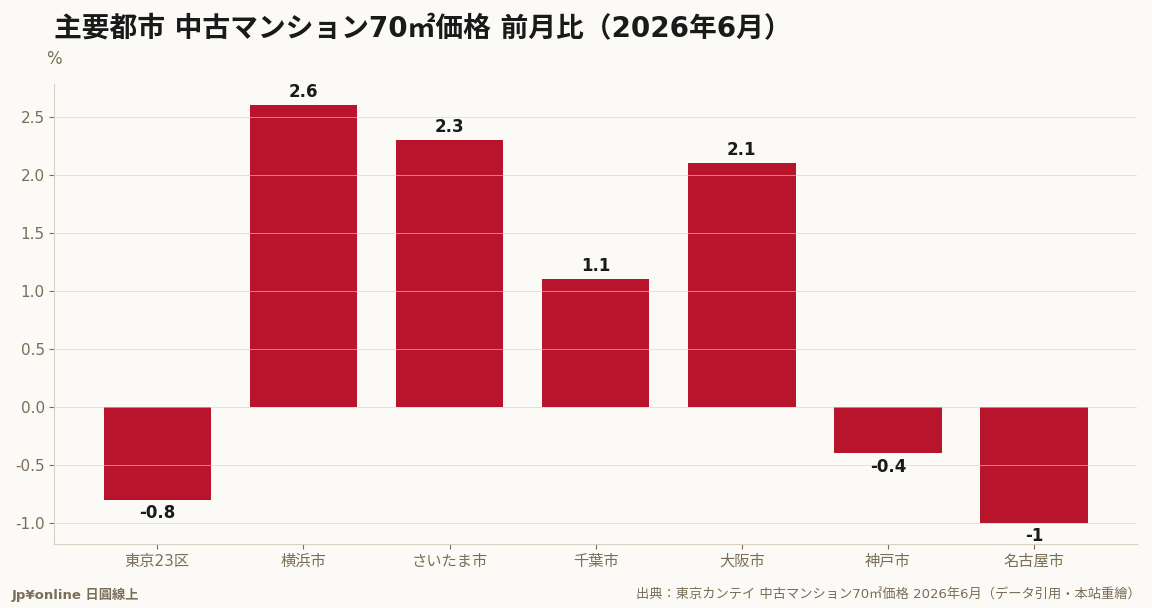
The gap between Kantei and REINS data confirms that while opening prices continued to rise in May, actual transaction prices began to fall. This June's report shows a closing of this gap with Kantei prices declining for the first time in 23区, following the textbook sequence of market adjustment: volume contraction → price decline → opening prices decline. The current adjustment is limited to the center of town; areas like Yokohama and Saitama continue to see strong demand without signs of adjustment.
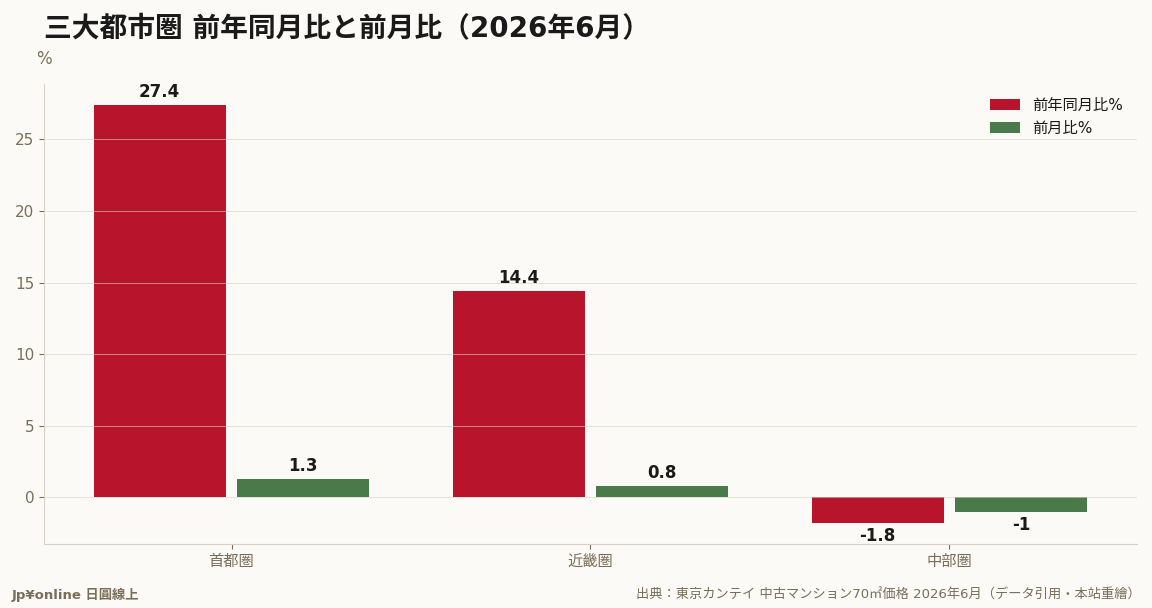
A 26-month period of increase in 23区 prices ended with a negative month, but this does not necessarily indicate a trend. However, the timing is significant as it coincides with increases in unsold new inventory and decreases in transaction volumes according to REINS data. Kantei's 127,410,000 yen still shows a year-over-year increase of 23.3%, indicating that this drop only reduces the peak of the bubble rather than reaching a correction level.
For Taiwanese readers: three key points. Negotiation opportunities have emerged in the central area; outer regions like Yokohama and Saitama are still setting new highs, so sellers will not lower their prices. Sellers should now focus on pricing strategies that align with actual transaction prices to avoid overpricing. Similarly budgeted areas such as Kanagawa, Saitama, and Osaka offer better value due to more stable price-to-value ratios.